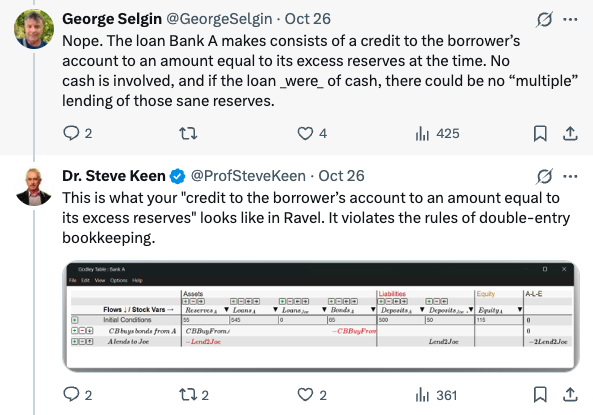
According to Steve, “George asserted banks could use reserves to make loans”. And yet George said “they can use [reserves] to finance loans”. [Emphasis added]. If the nub of the issue is whether reserves are being used as a direct source of fundings, this might not be a mere quibble. The subtle way in which Steve misrepresented George’s statement may in fact be telling.
I asked Steve to provide some context, because I want to avoid a situation where we spoke at cross purposes. And although I do not think that the monetary regime necessarily changes the logical coherence of the MM model, I felt it was important to agree on whether we were talking about the current system (where banks are not required to keep a certain proportion of deposits as reserves) or the previous system (where mandatory reserve requirements did play a role in monetary policy). So here is the conversation (link):
Anthony: I think the best explanation for how banks make loans depends on the monetary regime (e.g. whether there are mandatory reserve requirements, whether interest is paid on reserves, whether the supply of reserves is a policy objective or not). So I need more context to answer.
Steve: Do banks use reserves to make loans (a) with mandatory reserve requirements and (b) without interest paid on reserves and (c) when the supply of reserves is not a policy objective?
Anthony: I think that depends on what you mean by "use reserves to make loans". Do you agree that there's a difference between (1) immediately passing on newly obtained reserve balances to a customer; and (2) those reserves forming part of their constraint on lending.
Steve: Yes.
Anthony: Ok, and is the latter factually correct?
Steve: No
I found this answer interesting, because I drew a distinction around what I anticipated Steve would object to (that banks use reserves as a direct source of funding for deposits) and what I think is more defendable (that mandatory reserve requirements mean that reserves serve as a constraint on lending). So this was worth pursueing.
Anthony: So what are the main constraints on bank lending, when reserve requirements are mandated, if not reserves?
Steve: The willingness of banks to lever up (when creating loans) relative to their their equity, which is pro-cyclical.
Anthony: And does creating loans affect their reserve ratio?
At this point Steve simply posted a link to a CNBC article by John Carney called “Basics of Banking: Loans Create a Lot More Than Deposits”. I wasn’t sure if this was because he didn’t want to admit that yes indeed creating loans affects the reserve ratio, therefore reserves form part of a constraint on lending, therefore I was right. So I persevered:
Anthony: Are you saying, "yes it does"?
Steve: No it doesn't. But loans can trigger reserve requirements and equity raising after the event. You have the causal sequence backwards.
I didn’t, because my causal sequence started with loans.
Anthony So we agree that lending decisions have to give consideration to reserve balances?
But Steve wouldn’t be drawn! He said:
Steve: “You tell me whether you agree that loans create deposits first.”
I thought I had already dealt with that, so replied:
Anthony: I've already said, "A bank decides to extend a loan by crediting a deposit account". Does that deal with your question?
Which he interpreted to be confirmation that he was right all along and that the conversation was now over.
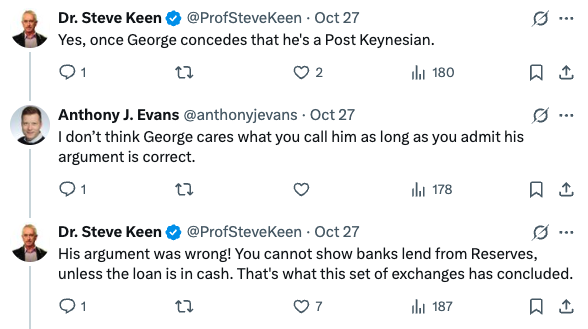
Steve: Yes. With reserves paying no role. So we’re agreed: banks create money by lending, and the money multiplier, fractional reserve banking, and loanable funds models are all false. Thanks. Now I’ll get in with my day.
But not so fast! We were actually very close to resolving the issue.
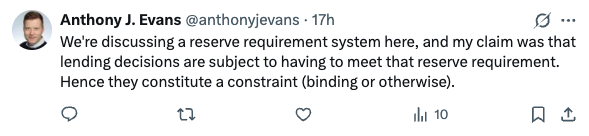
Anthony: Do you accept that lending decisions have to give consideration to reserve balances? (particularly in the context of mandatory reserve requirements)
Steve: Yes. They are a classic non-binding constraint, except for banks that are going under, like Northern Rock.
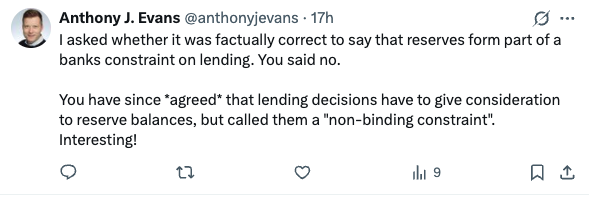
Anthony: Ok, so you accept that reserves *do* form a constraint on lending, but that ordinarily it is non-binding.
At this point the author of the CNBC article jumped in, and asked me:
John: Can you explain how you think they “form a constraint on lending” today? Or even under a reserve requirement system?
And Steve used that as an opportunity to bow out.
Steve: Tag team time... Over to you John!
Note how Steve’s position changed subtly (from “not a constraint” to “a non-binding constraint”) and instead of exploring what this (potentially critical) difference was, he attempted to shift the conversation away from answering my question (twice) and said that he would no longer respond (twice).
Here is my reply to Steve (which hasn’t been answered):

























Quisque iaculis facilisis lacinia. Mauris euismod pellentesque tellus sit amet mollis.